
26 posts on "new york fed"
November 18, 2020
The Impact of Natural Disasters on the Corporate Loan Market
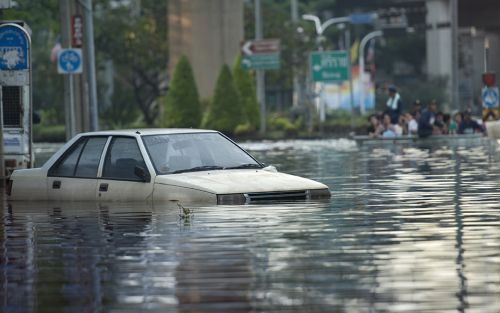
Natural disasters are usually associated with an increase in the demand for credit by both households and companies in the affected regions. However, if capacity constraints preclude banks from meeting the local increase in demand, the banks may reduce lending elsewhere, thus propagating the shock to unaffected areas. In this post, we analyze the corporate loan market and find that banks, particularly those with lower capital, reduce credit provisioning to distant regions unaffected by natural disasters. We also find that shadow banks only partially offset the reduction in bank credit, so borrowers in regions unaffected by natural disasters experience a decline in credit supply.
August 27, 2020
Tracking the Spread of COVID‑19 in the Region
The New York Fed today unveiled a set of charts that track COVID-19 cases in the Federal Reserve’s Second District, which includes New York, Northern New Jersey, Fairfield County Connecticut, Puerto Rico, and the U.S. Virgin Islands. These charts, available in the Indicators section of our Regional Economy webpage, are updated daily with the latest data on confirmed COVID-19 cases from The New York Times, which compiles information from state and local health agencies. Case counts are measured as the seven-day average of new reported daily cases and are presented on a per capita basis to allow comparisons to the nation and between communities in the region. Recent data indicate that after spiking to extraordinary levels in April, new cases have remained relatively low and stable in and around New York City, and in upstate New York. By contrast, cases have been trending higher in Puerto Rico and the U.S. Virgin Islands since mid-July.
June 30, 2020
Leverage Ratio Arbitrage All Over Again
Leverage limits as a form of capital regulation have a well-known, potential bug: If banks can’t lever returns as desired, they can boost returns on equity by shifting toward riskier, higher yielding assets. That reach for yield is the leverage rule “arbitrage.” But would banks do that? In a previous post, we discussed evidence from our working paper that banks did do just that in response to the new leverage rule that took effect in 2018. This post discusses new findings in our revised paper on when and how banks arbitraged.
June 16, 2020
Finally, Some Signs of Improvement in the Regional Economy
The Federal Reserve Bank of New York’s June business surveys show some signs of improvement in the regional economy. Following two months of unprecedented decline due to the coronavirus pandemic, indicators of business activity point to a slower pace of contraction in the service sector and signs of a rebound in the manufacturing sector. Even more encouraging, as the regional economy has begun to reopen, many businesses have started to recall workers who were laid off or put on furlough since the start of the pandemic. Some have even hired new workers. Moreover, businesses expect to recall even more workers over the next month. Looking ahead, firms have become increasingly optimistic that conditions will improve in the coming months.
Posted at 8:30 am in Employment, Human Capital, Labor Market, New Jersey, New York, Pandemic, Regional Analysis, Unemployment | Permalink
May 7, 2020
Translating Weekly Jobless Claims into Monthly Net Job Losses
News headlines highlighting the loss of 26 million jobs (so far) underscore the massive shock that has hit the U.S. economy and the dislocation, hardship, and stress it has caused for so many American workers. But how accurately does this number actually capture the number of net job losses? In this post, we look at some of the statistical anomalies and quirks in the weekly claims series and offer a guide to interpreting these numbers. What we find is that the relationship between jobless claims and payroll employment for the month can vary substantially, depending on the nature, timing, and persistence of the disaster.
Posted at 7:00 am in Human Capital, Labor Market, Pandemic, Regional Analysis, Unemployment | Permalink | Comments (4)
May 6, 2020
Where Have the Paycheck Protection Loans Gone So Far?
The Paycheck Protection Program (PPP) is a central piece of the CARES Act. In the program’s first round, $349 billion in forgivable government-guaranteed loans were extended to small businesses to cover costs related to payroll and utilities, as well as mortgage and rent payments. The program opened for applications on April 3 and was oversubscribed by April 16. Because of its popularity, lawmakers passed a new bill replenishing the fund with another $310 billion and the Small Business Administration (SBA) started approving loans again on April 27. With a new round of PPP lending underway, it is natural to examine the allocation of credit in the first round and ask: Have PPP loans gone to the areas of the country and sectors of the economy hardest hit by COVID-19?
April 16, 2020
New York Fed Surveys: Business Activity in the Region Sees Historic Plunge in April
Indicators of regional business activity plunged to historic lows in early April, as efforts to slow the spread of the coronavirus kept many people at home and shut down large parts of the regional economy, according to the Federal Reserve Bank of New York’s two business surveys. The headline index for both surveys plummeted to nearly -80, well below any historical precedent including the depths of the Great Recession. About 60 percent of service firms and more than half of manufacturers reported at least a partial shutdown of their operations thus far. Layoffs were widespread, with half of all businesses surveyed reporting lower employment levels in early April.
March 4, 2020
Searching for Higher Job Satisfaction
Using data from the New York Fed’s Survey of Consumer Expectations, these Liberty Street Economics authors document the heterogeneity in job satisfaction among U.S. workers and in their preferences for various nonwage benefits, and discuss the impact of these preferences on job search behavior.
February 13, 2020
Firm‑Level Shocks and GDP Growth: The Case of Boeing’s 737 MAX Production Pause
Events specific to large firms can have significant effects on the macroeconomy. The recent pause in Boeing’s 737 MAX production is a striking example of such an event or “shock.” This post provides a back-of-the envelope calculation of how the “737 MAX shock” could impact U.S. GDP growth in the first quarter of 2020.
Posted at 7:00 am in Macroeconomics | Permalink
September 5, 2018
Education’s Role in Earnings, Employment, and Economic Mobility
Amid dialogue about the soaring student loan burden, questions arise about how educational characteristics (school type, selectivity, and major) affect disparities in post-college labor market outcomes. In this post, we specifically explore the impact of such school and major choices on employment, earnings, and upward economic mobility. Insight into determinants of economic disparity is key for understanding long-term consumption and inequality patterns. In addition, this gives us a window into factors that could be used to ameliorate income inequality and promote economic mobility.
Posted at 7:00 am in Education, Equitable Growth, Human Capital, Inequality, Labor Market | Permalink
 RSS Feed
 Follow Liberty Street Economics