
312 posts on "Financial Markets"
September 30, 2026
The Role of Repos in Monetary Policy Implementation
In the first two posts of this three-part series, we discussed private market participants that are active in repo markets for profit-making motives. Central banks are also active repo market participants, but their reasons often differ from those of private participants. In today’s post, we discuss how central banks use repos to manage liquidity in the financial system and implement monetary policy.
Posted at 7:00 am in Central Bank, Financial Markets, Monetary Policy, Repo | Permalink | Comments (0)
September 28, 2026
Who’s Borrowing and Lending in Repo Markets?
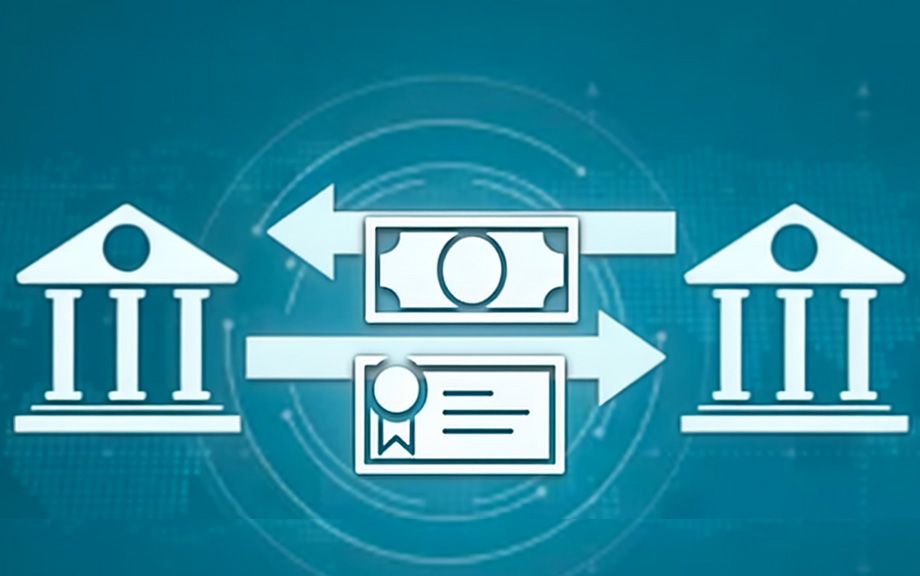
Repo markets play a vital role in the U.S. financial system. In this three-part series, we examine who participates in these markets, what trade-offs influence how different repo segments are structured, and why repos matter for monetary policy. Today’s post introduces repo transactions, focusing on the major private-sector participants and why they engage in these markets.
September 22, 2026
Treasury Trading at the Close
In past work, we showed that trading in U.S. Treasury securities is becoming increasingly concentrated on the last trading day of each month. In this post, we show that trading is also becoming more concentrated around the designated pricing, or “strike,” times for fixed-income indexes. The concentration is especially pronounced on month-end trading days. We also document a marked shift in trading activity from around 3 p.m. (ET) to around 4 p.m. after a major fixed-income index provider moved its strike time from 3 p.m. to 4 p.m. in January 2021.
August 12, 2026
Does the Equity Term Structure Respond to Monetary Policy Shocks?
A long-standing body of research, inspired by Bernanke and Kuttner (2005), has documented the effects of Fed interest rate surprises on stock markets. While stock markets provide valuable information about the investor risk premium and dividend growth expectations, researchers have only recently developed more comprehensive tools to estimate the term structure of equity risk premia and dividend growth expectations across a broad range of maturities. In this post, we investigate the impact of monetary policy surprises (or shocks) on short- and long-term estimates of risk premia and growth expectations through the lens of the Giglio, Kelly, and Kozak (2024) model.
Posted at 7:00 am in Financial Markets | Permalink
August 10, 2026
Stripping STRIPs Trading Activity
In March 2020, the Financial Industry Regulatory Authority (FINRA) began reporting aggregate trading volume for securities issued by the U.S. Treasury Department. The public data do not, however, include information about the trading activity of Separate Trading of Registered Interest and Principal of Securities (STRIPS). STRIPS are created from existing Treasury securities and offer risk […]
August 4, 2026
A Window into Bond Investors’ Uncertainty About R‑Star
Monetary policymakers closely monitor the term structure of sovereign bond yields to uncover market participants’ beliefs about the future monetary policy stance, inflation, and activity. A particular object of interest is the natural real rate of return, or “r-star,” which acts as a guide for monetary policy decisions. Numerous papers have questioned how much information investors possess, and how precisely they know r-star. In this post based on a recent Staff Report, we explore what the term structure of interest rates can teach us about r-star and its perception by investors.
Posted at 7:00 am in Central Bank, Financial Markets, Inflation, Macroeconomics, Monetary Policy | Permalink
July 1, 2026
The Disappearing Overnight Drift
In a 2021 Liberty Street Economics post, we documented the “overnight drift”—a large, persistent return to holding U.S. equity futures in the narrow window between 2:00 and 3:00 a.m. Eastern time, when European equity markets open. Five additional years of data later, that pattern appears to have faded: the 2:00–3:00 window that previously generated roughly 3.7 percent per annum has averaged close to zero since 2021. In this post, we revisit the overnight drift in light of the post-publication sample and use our inventory-risk framework to ask which of three observable channels—the dispersion of closing order imbalances, the level of return variance, or the risk-bearing capacity of liquidity providers—accounts for the change.
February 24, 2026
Estimating the Term Structure of Corporate Bond Risk Premia
Understanding how short- and long-term assets are priced is one of the fundamental questions in finance. The term structure of risk premia allows us to perform net present value calculations, test asset pricing models, and potentially explain the sources of many cross-sectional asset pricing anomalies. In this post, I construct a forward-looking estimate of the term structure of risk premia in the corporate bond market following Jankauskas (2024). The U.S. corporate bond market is an ideal laboratory for studying the relationship between risk premia and maturity because of its large size (standing at roughly $16 trillion as of the end of 2024) and because the maturities are well defined (in contrast to equities).
January 7, 2026
What Is a Carbon Tariff and Why Is the EU Imposing One?
The European Union has been an early adopter of carbon policies, with the introduction of the EU Emissions Trading System (ETS) in 2005. This scheme sets a common price for carbon and is applied to the most polluting manufacturing sectors. By increasing the cost of emissions-intensive production, the system incentivizes firms to decrease their use of fossil fuels. However, as we show in a companion post, the policy’s impact was moderated by firms increasing their reliance on high-emissions imports. To eliminate this workaround, the EU will expand the ETS to imports in 2026, through the Carbon Border Adjustment Mechanism (CBAM). The CBAM will essentially put a tariff on imported goods based on their carbon content. Our recent work provides a quantitative analysis of how the ETS and CBAM affect firms’ supply choice decisions, and the resulting changes in domestic prices and emissions.
What Can Undermine a Carbon Tax?
Several countries have implemented a carbon tax or cap-and-trade system to establish high carbon prices and create a disincentive for the use of fossil fuels. Essentially, the tax encourages firms to substitute toward low carbon emission energy. Costs also rise for firms down the supply chain that use production inputs with high-emission content, so the total impact of a carbon tax can be large. In practice, however, firms also have an incentive to find an offset to a carbon tax. In this post, based on our recent work, we present evidence of one such adaptation strategy. We show that French firms increased their imports of high-emission inputs from suppliers outside the European Union’s cap-and-trade system, known as the EU Emissions Trading System (EU ETS), reducing the effectiveness of this approach to cutting carbon emissions—an adaptation strategy that leads to “carbon leakage.” To help stop this leakage, the EU is implementing a “carbon tariff” in 2026, which is the topic of a companion post.
 RSS Feed
 Follow Liberty Street Economics