
26 posts on "Tariffs"
October 6, 2026
How Fast Do Tariffs Pass Through into Consumer Prices?
There has been a lot of interest in how tariffs affect consumer prices (for example, Cavallo et al. 2021, 2025). In this post, we present results from our new research paper that estimates the effects of the 2025-26 tariffs on retail consumer prices. We find that for every percentage point increase in average tariffs, consumer goods prices increase by about a quarter of a percent after one year. Roughly two-thirds of the effect arises because tariffs raise the prices of imported consumer goods. The remaining third arises indirectly: tariffs increase the prices of goods made in the U.S. because producers pay more for imported parts and materials, and because producers raise their markups when competing imports cost more. The effects differ in their timing. Prices of imported goods respond quickly to tariffs, while prices of U.S.-made goods adjust over six to twelve months as higher costs move through the supply chain.
July 9, 2026
Effect of Tariffs on U.S. Small Businesses
How has the recent implementation of tariffs affected small businesses? Due to lack of data, little is known about this issue. In this Liberty Street Economics post, we use data from the 2025 edition of the Small Business Credit Survey (SBCS) to explore this question for businesses nationally and in the Second District (defined, for the purpose of this study, as New York, New Jersey, and Connecticut). We find that the majority of national firms in the goods and retail sectors reported experiencing financial challenges due to tariffs in 2025, with even larger shares of regional firms doing so. In response, about 80 percent of national and regional firms passed on at least some of the higher costs of imported inputs to customers, while about 60 percent absorbed some of the costs, as many firms did some of both. Firms that faced greater tariff challenges in 2025 were more pessimistic about employment and revenues in 2026.
July 8, 2026
More Tariff Pass‑Through Is in the Pipeline
The past year brought dramatic changes to U.S. trade policy, including sweeping new tariffs, as well as a Supreme Court decision that further reshaped the tariff landscape. Many businesses saw their costs increase significantly and faced complex decisions about whether to absorb the tariffs through lower profit margins, raise their prices to recover the higher costs, or some combination of the two. Last year, we found that most businesses had passed on at least some of these higher costs to their customers through higher prices. Now, over a year later, have businesses finished adjusting prices, or do further tariff-induced price increases lie ahead? Our latest regional business surveys reveal that nearly half of firms that have paid tariffs still plan additional price increases to offset these costs, with some expecting to raise prices six months or more in the future.
May 4, 2026
In What Ways Has U.S. Trade with China Changed?
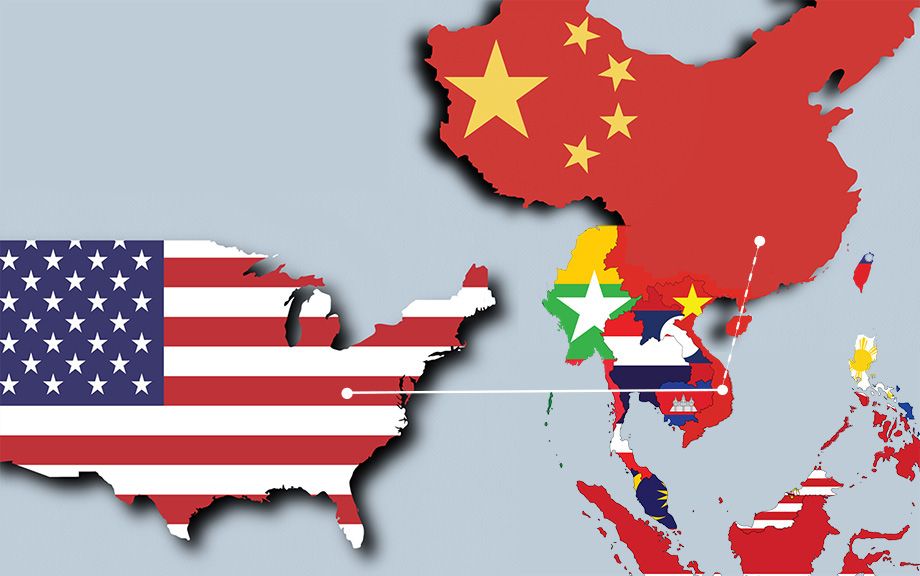
Over the past year, U.S. trade policy with China has undergone enormous changes, but with surprisingly little effect on overall trade balances. In fact, the U.S.’s twelve-month trade deficit, while highly volatile due to import front-running early in the year, ended 2025 at $1.2 trillion, almost unchanged from 2024. At the same time, China’s trade surplus with the world actually increased from $1 trillion to $1.2 trillion. However, when looking at changes between individual countries, one sees large shifts in bilateral balances. In this post, we will focus on changing trade flows between the U.S., China, and southeast Asia.
Posted at 7:00 am in Artificial Intelligence (AI), International Economics, Tariffs | Permalink | Comments (2)
February 12, 2026
Who Is Paying for the 2025 U.S. Tariffs?
Over the course of 2025, the average tariff rate on U.S. imports increased from 2.6 to 13 percent. In this blog post, we ask how much of the tariffs were paid by the U.S., using import data through November 2025. We find that nearly 90 percent of the tariffs’ economic burden fell on U.S. firms and consumers.
October 6, 2025
A Country‑Specific View of Tariffs

U.S. trade policy remains in flux. Nevertheless, important elements of the new policy regime are apparent in data through July. What stands out are the large differences in realized tariff rates by trading partner, ranging from less than 5 percent for Canada and Mexico to 15 percent for Japan and to 40 percent for China. This post shows that the bulk of cross-country differences in tariff rates is explained by two factors: the U.S.-Canada-Mexico free trade agreement and differing sales shares in tariff-exempt categories.
June 4, 2025
Are Businesses Absorbing the Tariffs or Passing Them On to Their Customers?
U.S. import tariffs increased to historically high rates in recent months, raising the costs of many imported inputs businesses use. Businesses subject to these higher costs have been faced with difficult and complex decisions about whether to absorb the tariffs through lower profits, raise their prices to recover the higher costs, or some combination of both. These decisions are influenced by the degree of competition in the marketplace, potential customer reactions, and the ability to maintain profit margins, among other factors. Our May survey of businesses in the New York–Northern New Jersey region asked firms about the tariffs they faced, recent changes in the cost of imported goods, and whether they were passing on tariff-induced cost increases to their customers. Results indicate most businesses passed on at least some of the higher tariffs to their customers, with nearly a third of manufacturers and about 45 percent of service firms fully passing along all tariff-induced cost increases by raising their prices.
April 24, 2025
Gauging the Strength of China’s Economy in Uncertain Times
Amid increasing pressure on the Chinese economy from China’s trade conflict with the U.S., assessing the strength of the Chinese economy will be an important watch point. In this post, we provide an update on China’s recent economic performance and policy changes. While China is likely to counter growth headwinds from the escalating trade tensions with additional policy stimulus, the country’s complex fiscal dynamics and the varying interpretations of the strength of its economic growth made judgments of the efficacy of China’s policy response challenging even in a more predictable environment. In this respect, we argue that aggregate credit is a simple and effective measure to gauge policy stimulus in China. At present, China’s “credit impulse”—the change in the flow of new aggregate credit to the economy relative to GDP—appears likely sufficient to allow it to muddle through with steady but not strong growth over the next year despite the intensifying trade conflict.
March 5, 2025
Firms’ Inflation Expectations Have Picked Up
Editors note: Since this post was published, we clarified language in the first paragraph about year-ahead expectations for manufacturing and service firms in the 2025 survey. We also corrected the y-axis range of Chart 2. (March 5, 11 a.m.)

After a period of particularly high inflation following the pandemic recession, inflationary pressures have been moderating the past few years. Indeed, the inflation rate as measured by the consumer price index has come down from a peak of 9.1 percent in the summer of 2022 to 3 percent at the beginning of 2025. The New York Fed asked regional businesses about their own cost and price increases in February, as well as their expectations for future inflation. Service firms reported that business cost and selling price increases continued to moderate through 2024, while manufacturing firms reported some pickup in cost increases but not price increases. Looking ahead, firms expect both cost and price increases to move higher in 2025. Moreover, year-ahead inflation expectations have risen from 3 percent last year at this time to 3.5 among manufacturing firms and 4 percent among service firms, though longer-term inflation expectations remain anchored at around 3 percent.
February 26, 2025
U.S. Imports from China Have Fallen by Less Than U.S. Data Indicate

With new tariffs on China back in the headlines, this post seeks to offer some perspective on how much China’s exports have really been affected by multiple rounds of U.S. tariffs and export restrictions over the past seven years. The key takeaway is that U.S. imports from China have decreased by much less than has been reported in official U.S. statistics. As a result, the recent tariff increase on China could have a larger impact on the U.S. economy than is suggested by official U.S. data on the China import share, especially if favorable tariff treatment for direct-to-consumer imports is ended.
 RSS Feed
 Follow Liberty Street Economics