
234 posts on "Household Finance"
November 10, 2026
A Look at the Wider Divide in Credit Card Delinquency by Income

Credit card delinquency rose sharply between 2022 and 2024, and the increase was steepest among borrowers in lower-income neighborhoods. Here, we check in on credit card performance by neighborhood income and trace when the borrowers who are now struggling with their payments were issued cards. We find that during the pandemic, an increasing share of new credit cards went to borrowers with lower incomes and credit scores, and those accounts are now showing higher levels of distress.
November 4, 2026
How Market Position Shapes Credit Card Interest Rates
Why is it that two borrowers who look much alike can be offered very different rates when applying for a credit card? In a recent paper, we address this question by examining how the rate offered changes when the lender’s funding cost falls. Data on 14 million newly issued cards show that when a lender’s funding costs decline, the lender passes less of that decline on to the offer rate when it holds a large market share. That is, two borrowers with similar credit scores and incomes borrowing from the same lender can see noticeably different interest rates on the credit card they are applying for.
Posted at 7:00 am in Credit, Financial Markets, Household Finance, Macroeconomics | Permalink | Comments (0)
October 5, 2026
Insured, but Still on the Hook: Who Bears the Most Risk in Homeowner’s Insurance?
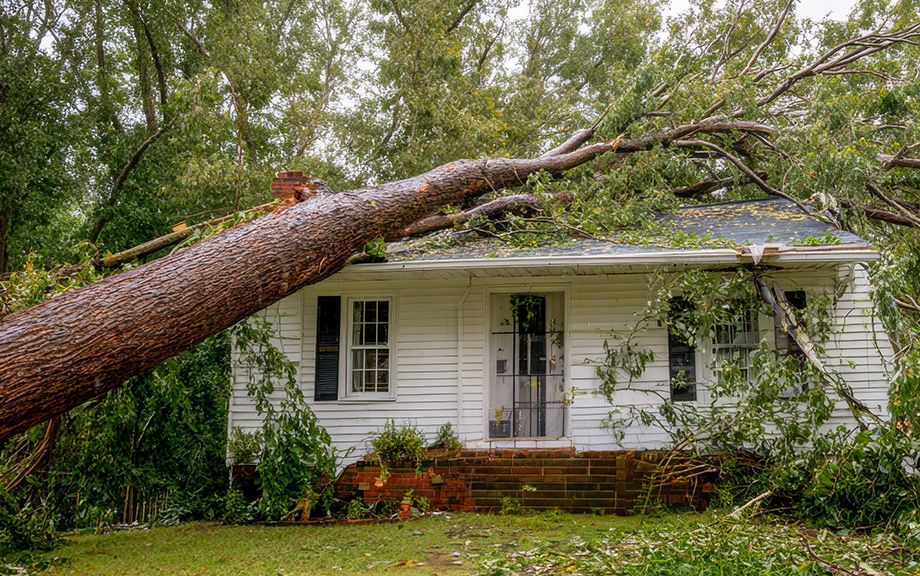
In an April post, using millions of homeowner’s insurance contracts matched with property-level exposure and disaster risk, we showed that although households are insured, they are still “on the hook” because deductibles and coverage limits leave homeowners responsible for part of a loss. Because insurers cannot perfectly observe how well homeowners maintain or protect their properties (a problem known as “moral hazard”), contract terms such as deductibles can play an important role in balancing risk sharing and incentives. By requiring homeowners to bear part of a loss, insurers can preserve incentives for policyholders to take actions that reduce damage risk. In this post, we quantify the cost of keeping homeowners on the hook. How costly is moral hazard in homeowner’s insurance? How much risk must households retain to preserve these incentives? And, importantly, who ultimately bears that residual risk? The short answer is that keeping homeowners on the hook costs insurers relatively little, but it leaves households with substantial risk, especially those least able to absorb a large loss.
August 19, 2026
Has Broader Stock Market Participation Changed How Interest Rates Affect the Economy?
Stock market participation in the U.S. has changed dramatically over the past four decades. In the mid-1980s, fewer than 30 percent of households held equity. By the early 2000s, more than half of U.S. households owned equity, either directly or through mutual funds, 401(k)s, and IRAs. As participation widened, the way stock market fluctuations passed through to household spending may have changed, with potential implications for how the broader economy behaves. An argument can be made that the rise in equity market participation has dampened the response of output to interest rate changes as stock market fluctuations are now spread across a larger share of households, moderating movements in consumer spending, asset prices, and investment spending.
August 11, 2026
How Distressed Are Consumers? Reconciling Diverging Credit Card Delinquency Measures
Total debt balances declined slightly by $13 billion in the second quarter of 2026, according to the latest Quarterly Report on Household Debt and Credit from the New York Fed’s Center for Microeconomic Data. Mortgage and student loan balances saw a small decline, while there were increases across other debt products. Delinquency rates across most products remained fairly stable. Still, between 2022:Q3 and 2026:Q1, the percentage of credit card balances 90+ days delinquent rose from 7.6 percent to 12.8 percent, prompting concerns that Americans are falling behind on their debt payments at rates not seen since the Great Recession. Yet the flow delinquency rate—which captures the rate of new delinquencies—has remained relatively stable for almost two years. In this post, we use data from the New York Fed Consumer Credit Panel (CCP) to better understand the state of the consumer, and to explain the difference between our two measures of delinquency. We find that the stock delinquency rate is rising because of a pool of stale, charged-off debts that lenders have been reporting for longer durations, rather than a fundamental worsening in the incidence of delinquency.
June 3, 2026
The Unintended Effects of Interest Rate Caps: Credit Reallocation to Safer Borrowers

Several states have recently capped consumer loan rates with the stated purpose of protecting borrowers. In a recent Staff Report, we study how these interventions have played out in three states. In our first post about that study, we showed that rate caps lead riskier borrowers to face rationing in the credit market. One question that naturally arises is what lenders do with the credit they used to provide to high-risk borrowers before the caps were imposed. Lenders that lend exclusively to high-risk borrowers (at rates above the cap) may decide to stop lending to high-risk borrowers in that state. Others, however, may try to change their “credit box” by lending more to somewhat safer borrowers. In this post, we will try to understand how lenders reallocate credit after usury limits are implemented.
Posted at 7:01 am in Household Finance | Permalink
The Unintended Effects of Interest Rate Caps: Credit Rationing for Risky Borrowers
In imperial China, 3 percent was the maximum legal monthly loan rate; charging more was punishable by 40 to 100 blows with the “light cane.” (Rockoff 2003) Centuries later, many U.S. states are imposing the same cap (without corporal penalties) on alternative credit providers, such as payday, installment, and auto-title lenders, with the goal of lowering credit costs and delinquency for the high-risk borrowers that rely on these funding sources. A concern, however, is that lenders will simply refuse to lend to these borrowers at lower interest rates. Our recent Staff Report studies how interest rate caps have played out in several states that recently adopted them. Using household-level data from a major credit bureau, we find that loan balances for the riskiest borrowers declined substantially relative to counterparts in states without caps. Despite taking on less debt, these borrowers did not experience an improvement in delinquencies.
Posted at 7:00 am in Household Finance | Permalink
May 27, 2026
Food Insecurity and Consumer Pessimism
Current discussions regarding a bifurcated U.S. economy highlight the increasing economic divide between lower- and higher-income Americans in spending and earnings growth and wealth accumulation. While many households are doing fine and economic activity overall has been expanding at a solid pace, large segments of the population are facing high levels of economic insecurity and financial strain, and consumer sentiment on the whole has dropped to low levels. In this post, we use newly collected data from the Survey of Consumer Expectations (SCE) to update our 2020 analysis of disproportionate financial hardship experienced during the early pandemic and to investigate recent changes in food insecurity and broader economic strains. We then examine how food insecurity relates to the increase in consumer pessimism. We find a remarkable increase in food insecurity, particularly among lower-educated and lower-income households and households with young children. We document a contemporaneous increase in pessimism among the same groups, along with a sharp decline in job-finding expectations.
May 6, 2026
Same Shock, Different Roads? A K‑Shaped Pattern at the Pump
In March 2026, energy prices surged to a four-year high, driven by the Iranian closure of the Strait of Hormuz amid the ongoing conflict in the Middle East. In this Liberty Street Economics post, we use the new consumer spending module of the Economic Heterogeneity Indicators to analyze recent changes in nominal and real gas consumption across different income groups. We find that households had very different experiences with gasoline spending: in March, high-income households increased nominal spending the most and kept real consumption essentially unchanged, while low-income households decreased real consumption of gasoline but still saw sharply increased nominal spending because of the rise in gas prices. Therefore, with the sharp increases in gasoline prices in March, a K-shaped pattern in gasoline consumption emerged—showing faster consumption growth for high-income households relative to low-income households. These gasoline consumption patterns qualitatively match those following the increase in energy prices at the beginning of the Russia-Ukraine war in spring 2022, even though the gap in consumption trends during the current episode is quantitatively larger.
May 1, 2026
Explaining the K‑Shaped Economy: What’s Behind the Divide?
In our companion post, we used a new module of our Economic Heterogeneity Indicators (EHIs) to shed light on how recent retail spending growth has been driven by high-income households. This fact is consistent with the popular press’s idea of a “K-shaped economy” in which higher-income households experience faster growth in spending than lower-income households. In this post, we dive deeper into the reasons behind this divergence by analyzing for which goods this trend holds true and ask whether it can be explained by changes in wages, inflation, or wealth. We find that, since 2023, wealth has increased the most for high-income households, while inflation has risen the most for low-income households, with both factors helping explain the fact that real retail spending rose the most for high-income households. In contrast, earnings display a more mixed pattern, though earnings of the highest earners have grown more rapidly than earnings of the lowest earners.
 RSS Feed
 Follow Liberty Street Economics