
75 posts on "Financial Intermediation"
February 17, 2022
How (Un‑)Informed Are Depositors in a Banking Panic? A Lesson from History
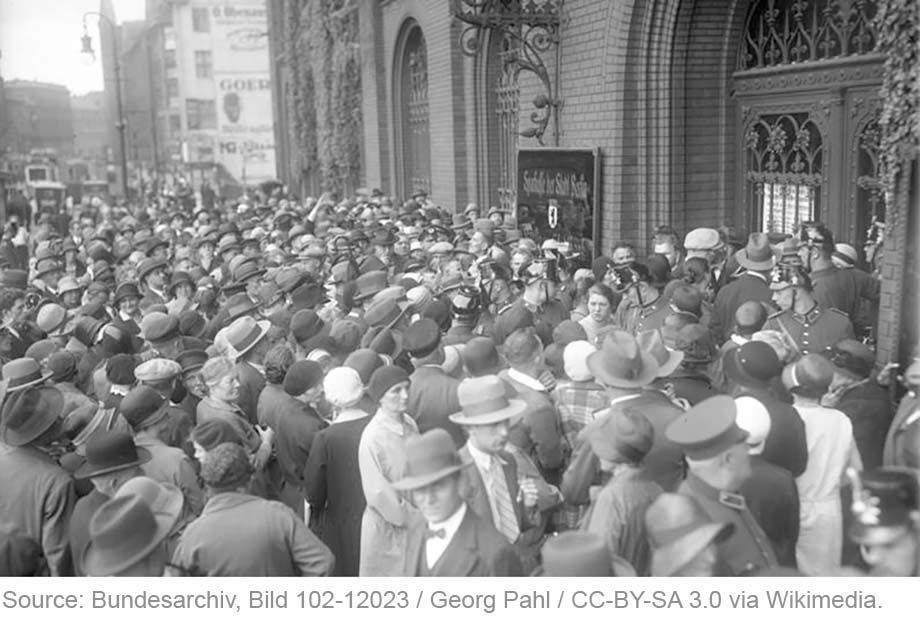
How informed or uninformed are bank depositors in a banking crisis? Can depositors anticipate which banks will fail? Understanding the behavior of depositors in financial crises is key to evaluating the policy measures, such as deposit insurance, designed to prevent them. But this is difficult in modern settings. The fact that bank runs are rare and deposit insurance universal implies that it is rare to be able to observe how depositors would behave in absence of the policy. Hence, as empiricists, we are lacking the counterfactual of depositor behavior during a run that is undistorted by the policy. In this blog post and the staff report on which it is based, we go back in history and study a bank run that took place in Germany in 1931 in the absence of deposit insurance for insight.
Posted at 7:00 am in Banks, Financial Institutions, Financial Intermediation, Panic, Systemic Risk | Permalink
January 31, 2022
Pricing Liquidity without Preemptive Runs
Prime money market funds (MMFs) are vulnerable to runs. This was dramatically illustrated in September 2008 and March 2020, when massive outflows from prime MMFs worsened stress in the short-term funding markets and eased only after taxpayer-supported interventions by the Treasury and the Federal Reserve. In this post, we describe how mechanisms like swing pricing that charge a price for liquidity can reduce the vulnerability of prime MMFs without triggering preemptive runs.
November 24, 2021
The Term Spread as a Predictor of Financial Instability
The term spread is the difference between interest rates on short- and long-dated government securities. It is often referred to as a predictor of the business cycle. In particular, inversions of the yield curve—a negative term spread—are considered an early warning sign. Such inversions typically receive a lot of attention in policy debates when they […]
November 22, 2021
Preemptive Runs and the Offshore U.S. Dollar Money Market Funds Industry
In March 2020, U.S. dollar-denominated prime money market funds (MMFs) suffered heavy outflows as concerns about the COVID-19 pandemic increased in the United States and Europe. Investors redeemed their shares en masse not only from funds domiciled in the United States (“domestic”) but also from offshore funds. In this post, we use differences in the regulatory regimes of domestic and offshore funds to identify the impact of the redemption gates and liquidity fees recently introduced as part of MMF industry reforms in both the United States and Europe.
October 18, 2021
Were Banks Exposed to Sell‑offs by Open‑End Funds during the Covid Crisis?
Should open-end mutual funds experience redemption pressures, they may be forced to sell assets, thus contributing to asset price dislocations that in turn could be felt by other entities holding similar assets. This fire-sale externality is a key rationale behind proposed and implemented regulatory actions. In this post, I quantify the spillover risks from fire sales, and present some preliminary results on the potential exposure of U.S. banking institutions to asset fire sales from open-end funds.
July 12, 2021
Tailoring Regulations
Regulations are not written in stone. The benefits derived from them, along with the costs of compliance for affected institutions and of enforcement for regulators, are likely to evolve. When this happens, regulators may seek to modify the regulations to better suit the specific risk profiles of regulated entities. In this post, we consider the Economic Growth, Regulatory Relief, and Consumer Protection Act (EGRRCPA) passed by Congress in 2018, which eased banking regulations for smaller institutions. We focus on one regulation—the Liquidity Coverage Ratio (LCR)—and assess how its relaxation affected newly exempt banks’ assets and liabilities, and the resilience of the banking system.
Posted at 7:00 am in Bank Capital, Banks, Financial Intermediation, Liquidity, Regulation | Permalink | Comments (2)
June 30, 2021
Hold the Check: Overdrafts, Fee Caps, and Financial Inclusion
The 25 percent of low-income Americans without a checking account operate in a separate but unequal financial world. Instead of paying for things with cheap, convenient debit cards and checks, they get by with “fringe” payment providers like check cashers, money transfer, and other alternatives. Costly overdrafts rank high among reasons why households “bounce out” of the banking system and some observers have advocated capping overdraft fees to promote inclusion. Our recent paper finds unintended (if predictable) effects of overdraft fee caps. Studying a case where fee caps were selectively relaxed for some banks, we find higher fees at the unbound banks, but also increased overdraft credit supply, lower bounced check rates (potentially the costliest overdraft), and more low-income households with checking accounts. That said, we recognize that overdraft credit is expensive, sometimes more than even payday loans. In lieu of caps, we see increased overdraft credit competition and transparency as alternative paths to cheaper deposit accounts and increased inclusion.
Banking the Unbanked: The Past and Future of the Free Checking Account
About one in twenty American households are unbanked (meaning they do not have a demand deposit or checking account) and many more are underbanked (meaning they do not have the range of bank-provided financial services they need). Unbanked and underbanked households are more likely to be lower-income households and households of color. Inadequate access to financial services pushes the unbanked to use high-cost alternatives for their transactional needs and can also hinder access to credit when households need it. That, in turn, can have adverse effects on the financial health, educational opportunities, and welfare of unbanked households, thereby aggravating economic inequality. Why is access to financial services so uneven? The roots to part of this problem are historical, and in this post we will look back four decades to changes in regulation, shifts in the ownership structure of retail financial services, and the decline of free/low-cost checking accounts in the United States to search out a few of the contributory factors.
Posted at 7:00 am in Banks, Credit, Financial Intermediation, Financial Markets, Inequality | Permalink
June 2, 2021
Sophisticated and Unsophisticated Runs
In March 2020, U.S. prime money market funds (MMFs) suffered heavy outflows following the liquidity shock triggered by the COVID-19 crisis. In a previous post, we characterized the run on the prime MMF industry as a whole and the role of the liquidity facility established by the Federal Reserve (the Money Market Mutual Fund Liquidity Facility) in stemming the run. In this post, based on a recent Staff Report, we contrast the behaviors of retail and institutional investors during the run and explain the different reasons behind the run.
Posted at 7:00 am in Financial Intermediation | Permalink
February 5, 2021
Up on Main Street
The Main Street Lending Program was the last of the facilities launched by the Fed and Treasury to support the flow of credit during the COVID-19 pandemic of 2020-21. The others primarily targeted Wall Street borrowers; Main Street was for smaller firms that rely more on banks for credit. It was a complicated program that worked by purchasing loans and sharing risk with lenders. Despite its delayed launch, Main Street purchased more debt than any other facility and was accelerating when it closed in January 2021. This post first locates Main Street in the constellation of COVID-19 credit programs, then looks in detail at its design and usage with an eye toward any future programs.
Posted at 7:00 am in Bank Capital, Banks, Central Bank, COVID-19 Facilities, Credit, Federal Reserve, Financial Institutions, Financial Intermediation, Financial Markets, Fiscal Policy, Monetary Policy, Pandemic | Permalink
 RSS Feed
 Follow Liberty Street Economics