
75 posts on "Financial Intermediation"
December 22, 2020
How Does Zombie Credit Affect Inflation? Lessons from Europe
Even after the unprecedented stimulus by central banks in Europe following the global financial crisis, Europe’s economic growth and inflation have remained depressed, consistently undershooting projections. In a striking resemblance to Japan’s “lost decades,” the European economy has been recently characterized by persistently low interest rates and the provision of cheap bank credit to impaired firms, or “zombie credit.” In this post, based on a recent staff report, we propose a “zombie credit channel” that links the rise of zombie credit to dis-inflationary pressures.
November 18, 2020
The Impact of Natural Disasters on the Corporate Loan Market
Natural disasters are usually associated with an increase in the demand for credit by both households and companies in the affected regions. However, if capacity constraints preclude banks from meeting the local increase in demand, the banks may reduce lending elsewhere, thus propagating the shock to unaffected areas. In this post, we analyze the corporate loan market and find that banks, particularly those with lower capital, reduce credit provisioning to distant regions unaffected by natural disasters. We also find that shadow banks only partially offset the reduction in bank credit, so borrowers in regions unaffected by natural disasters experience a decline in credit supply.
November 10, 2020
The Fed Funds Market during the 2007‑09 Financial Crisis
The U.S. federal funds market played a central role in the financial system during the 2007-09 crisis, because it was the market which provided banks with immediate liquidity, even late in the day. Interpreting changes in fed funds rates is notoriously difficult, however, as many of the economic drivers behind the rates are simultaneously changing. In this post, I highlight results from a working paper which untangles the impact of these economic drivers and measures their respective effects on the marketplace using data over a sample period leading up to and during the financial crisis. The analysis shows that the spread between fed funds sold and bought widened because of increases in counterparty risk. Further, there was a large increase in the supply of cash into this market, suggesting that banks viewed fed funds as a relatively safe place to invest cash in a crisis environment.
June 25, 2020
Insider Networks
Erol and Lee consider the cat-and-mouse game played between financial regulators and those attempting to trade on inside information, including how insiders might form networks in order to circumvent restrictions, and how regulators might cope with insiders’ tactics.
Posted at 7:00 am in Bank Capital, Banks, Central Bank, Financial Institutions, Financial Intermediation, Financial Markets, Regulation | Permalink
June 16, 2020
Outflows from Bank‑Loan Funds during COVID‑19
The COVID-19 pandemic has put significant pressure on debt markets, especially those populated by riskier borrowers. The leveraged loan market, in particular, came under remarkable stress during the month of March. Bank-loan mutual funds, among the main holders of leveraged loans, suffered massive outflows that were reminiscent of the outflows they experienced during the 2008 crisis. In this post, we show that the flow sensitivity of the loan-fund industry to the COVID-19 crisis (and to negative shocks more generally) seems to be even greater than that of high-yield bond funds, which also invest in high-risk debt securities and have received much attention because of their possible exposure to run-like behavior by investors and their implications for financial stability.
Posted at 7:00 am in Crisis, Financial Institutions, Financial Intermediation, Liquidity, Pandemic | Permalink | Comments (2)
May 8, 2020
The Money Market Mutual Fund Liquidity Facility
To prevent outflows from prime and muni funds from turning into an industry-wide run after the COVID-19 outbreak, the Federal Reserve established Money Market Mutual Fund Liquidity Facility. This post looks at the Fed’s intervention, its goals, and the direct and indirect market effects.
Posted at 7:00 am in Central Bank, COVID-19 Facilities, Credit, Federal Reserve, Financial Institutions, Financial Intermediation, Financial Markets, Liquidity, Monetary Policy, Pandemic | Permalink
February 19, 2020
At the New York Fed: Fourteenth Annual Joint Conference with NYU‑Stern on Financial Intermediation
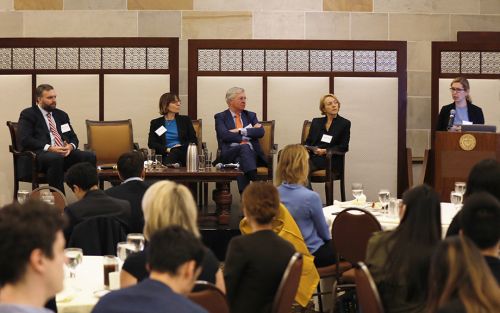
Blickle, Kovner, and Viswanathan share a synopsis of a recent conference featuring new research in financial intermediation and expert perspectives on corporate credit markets.
Posted at 7:00 am in Financial Intermediation | Permalink
February 3, 2020
Have the Risk Profiles of Large U.S. Bank Holding Companies Changed?
After the global financial crisis, regulatory changes were implemented to support financial stability, with some changes directly addressing capital and liquidity in bank holding companies (BHCs) and others targeting BHC size and complexity. Although the overall size of the largest U.S. BHCs has not decreased since the crisis, the organizational complexity of these same organizations has declined, with less notable changes being observed in their range of businesses and geographic scope (Goldberg and Meehl forthcoming). In this post, we explore how different types of BHC risks—risks that can influence the probability that a BHC is stressed, as well as the chance of systemic implications—have changed over time. The results are mixed: Levels of most BHC risks currently tend to be higher than in the years immediately preceding the crisis, but are markedly lower than the levels seen during and immediately following the crisis.
Posted at 7:00 am in Banks, Financial Institutions, Financial Intermediation, Regulation, Systemic Risk | Permalink
December 18, 2019
Banking System Vulnerability: Annual Update
A key part of understanding the stability of the U.S. financial system is to monitor leverage and funding risks in the financial sector and the way in which these vulnerabilities interact to amplify negative shocks. In this post, we provide an update of four analytical models, introduced in a Liberty Street Economics post last year, that aim to capture different aspects of banking system vulnerability.
Posted at 7:00 am in Bank Capital, Banks, Financial Institutions, Financial Intermediation, Liquidity, Systemic Risk | Permalink
December 16, 2019
Selection in Banking
Over the past thirty years, more than 2,900 U.S. banks have transformed from pure depository institutions into conglomerates involved in a broad range of business activities. What type of banks choose to become conglomerate organizations? In this post, we document that, from 1986 to 2018, such institutions had, on average, a higher return on equity in the three years prior to their decision to expand, as well as a lower level of risk overall. However, this superior pre-expansion performance diminishes over time, and all but disappears by the end of the 1990s.
 RSS Feed
 Follow Liberty Street Economics