
As in previous years, we provide in this post an update on the vulnerability of the U.S. banking system based on four analytical models that capture different aspects of this vulnerability. We use data through 2026:Q2 to update our analysis and discuss how the vulnerability measures have changed since our last update one year ago.
How Do We Measure Banking System Vulnerability?
We consider the following four measures to capture key dimensions of banking system vulnerability, based either on analytical frameworks developed by New York Fed staff or adapted from academic research. These measures were originally introduced in a Liberty Street Economics post in 2018 and have been updated annually since then. Our analysis draws on publicly available regulatory data on bank holding companies.
The four measures aim to capture capital, fire sale, liquidity, and run vulnerabilities—and the way in which they interact to amplify negative shocks. The chart below shows the evolution of these measures.
Capital Vulnerability Indexes
Capital gap, billions of dollars
Fire-Sale Vulnerability Index
Fraction of capital at risk
Liquidity Stress Ratio
Ratio of liquid liabilities to liquid assets
Run Vulnerability Index
Critical fraction of unstable funding
Source: Authors’ calculations, based on FR Y-9C reports.
Capital Vulnerability Indexes
We utilize two Capital Vulnerability Indexes to measure how well capitalized banks are likely to be after a severe macroeconomic shock. Constructed using the CLASS model, a top-down stress-testing model developed by New York Fed staff, these indexes measure the capital gap, defined as the aggregate amount of capital needed under a macroeconomic scenario to bring each bank’s Tier 1 common equity capital to at least 10 percent of its risk-weighted assets.
We calculate the Capital Vulnerability Indexes under two macroeconomic scenarios: one that replicates the conditions experienced during the 2007–09 financial crisis (“2008 redux”) and one that replicates the conditions experienced during the 2022 rise in interest rates (“2022 redux”). In the second scenario, unrealized gains and losses on securities held in the “available for sale” (AFS) and “held to maturity” (HTM) portfolios are fully reflected in banks’ capital levels.
These indexes have been stable or increasing over the last four quarters: under the “2008 redux” scenario, the capital gap stands at $16.9 billion (up from $1.9 billion in 2025:Q2), while based on the “2022 redux” scenario, the gap comes to $151.1 billion (little changed from $161.3 billion in 2025:Q2). These recent shifts can be explained by the decline in banks’ capital ratios, which, in the case of the “2022 redux” scenario, has been further compounded by the generalized increase in rates since March 2026.
The chart below documents the decomposition of the Capital Vulnerability Indexes into two main components at any given point in time, namely the starting level of capital and the capital depletion during the projection period. Note that the starting level of capital, especially once unrealized gains and losses on securities are taken into account, had been improving since 2023 as both (1) the level of actual bank capital has improved (light blue line) and (2) the unrealized losses on securities have decreased (further pushing the bright red line up). However, since the last update in 2025:Q2, there are early signs of a trend reversal, with capital levels deteriorating modestly.
Decomposition of the Capital Vulnerability Index
Ratio of capital to risk-weighted assets (percent)
Fire-Sale Vulnerability Index
This index, based on the article “Fire-Sale Spillovers and Systemic Risk,” captures the vulnerability of banks to a hypothetical system-wide asset fire sale. The scenario assumes a uniform shock to all asset values, incentivizing banks to sell assets in order to reduce their leverage. The spillover losses, resulting from the price impact of the asset sales, are calculated as a fraction of banks’ Tier 1 capital. The methodology uses the “fair value” for all securities and adjusts bank capital for unrealized losses (or gains).
The Fire-Sale Vulnerability Index is slightly higher compared to the previous annual update. The index has been on an unsteady uptrend since late 2024, suggesting a turn-around after the downtrend that followed the spike in 2022-24 (see the first chart in this post). The index is still at a moderate level by historical standards, but it remains elevated compared to the low levels observed between 2015 and 2022. The chart below decomposes the index into the size of the banking system (relative to the rest of the financial sector), its leverage, and its “connectedness” (capturing the commonality of asset liquidity, leverage, and size across banks). Both the increase in the index in 2022 and the evolution since then have been driven mainly by changes in leverage, measured at fair value.
Decomposition of the Fire-Sale Vulnerability Index
Normalized to 100 in 2006:Q1
Liquidity Stress Ratio
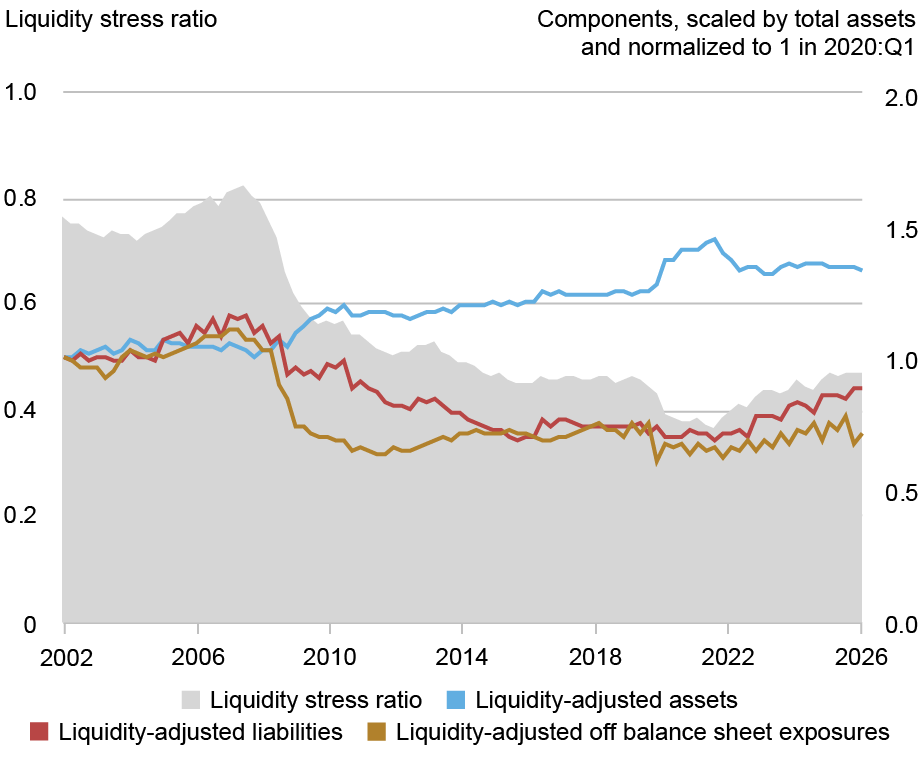
This ratio measures the potential liquidity shortfall of banks under conditions of liquidity stress as captured by the mismatch between liability-side (and off-balance-sheet) liquidity outflows and asset-side liquidity inflows. For each individual bank, it is defined as the ratio of runnability-adjusted liabilities plus off-balance-sheet exposures to liquidity-adjusted assets. The liabilities are adjusted for runnability by weighting each exposure category by its expected outflow rate, while the assets are adjusted for liquidity by weighting each asset category by its expected market liquidity. The liquidity stress ratio grows when expected funding outflows increase or assets become less liquid. The methodology accounts for unrealized losses or gains on all securities by using the fair value method, which implies an increase in the ratio when assets depreciate. The aggregate ratio is computed as a size-weighted average of each bank’s liquidity stress ratio.
The first chart in this post shows that the liquidity stress ratio is somewhat above the level of the previous annual update. It has been on an upward trend since 2022:Q1 and currently stands at a level not seen since 2014. The liquidity stress ratio is moderate by historical standards, being slightly above half of its 2007:Q3 peak but well above the low levels seen in 2020-21. The chart below plots the underlying components of the liquidity stress ratio. The significant rise in the ratio since early 2022 has been driven by a decline in liquid assets, coupled with an increase in unstable funding and off-balance-sheet exposures.
Decomposition of the Liquidity Stress Ratio
Run Vulnerability Index
This measure gauges a bank’s vulnerability to runs, taking into account both the bank’s liquidity and its solvency. We assume that a shock to assets and a concurrent loss of funding forces costly asset liquidations. Consequently, a bank can become insolvent due to a sufficiently bad asset shock, a sufficiently large loss of funding, or both. An individual bank’s run vulnerability is measured as the minimum fraction of unstable funding that the bank needs to retain in the stress scenario to prevent insolvency. The aggregate index is computed as a size-weighted average of banks’ run vulnerabilities. This methodology also uses the fair value for all securities.
The Run Vulnerability Index has increased compared to the previous annual update. The index has been on an unsteady upward trend since increasing sharply starting in 2022:Q1 and then slightly decreasing in 2023. Run vulnerability is currently moderate by historical standards but elevated compared to the low levels between 2015 and 2022. Considering the underlying components of run vulnerability (see the chart below), we see that higher illiquid assets, unstable funding and stress leverage have all contributed to the recent increase in the index.
Decomposition of the Run Vulnerability Index
Normalized to 0 in 2002:Q1
Final Words
Overall, three of our four measures show increasing trends in vulnerabilities of the overall banking system. While uniformly lower than the high levels seen in the run-up to the 2008–09 financial crisis, some of the measures have been higher in recent years than the low levels attained between 2015 and 2020.

Matteo Crosignani is a financial research advisor in the Federal Reserve Bank of New York’s Research and Statistics Group.

Thomas M. Eisenbach is a financial research advisor in the Federal Reserve Bank of New York’s Research and Statistics Group.

Fulvia Fringuellotti is a financial research economist in the Federal Reserve Bank of New York’s Research and Statistics Group.
How to cite this post:
Matteo Crosignani, Thomas M. Eisenbach, and Fulvia Fringuellotti, “Banking System Vulnerability: 2026 Update,” Federal Reserve Bank of New York Liberty Street Economics, November 12, 2026, https://doi.org/10.59576/lse.2026112
BibTeX: View |
Disclaimer
The views expressed in this post are those of the author(s) and do not necessarily reflect the position of the Federal Reserve Bank of New York or the Federal Reserve System. Any errors or omissions are the responsibility of the author(s).
 You can follow this conversation by subscribing to the comment feed for this post.
 RSS Feed
 Follow Liberty Street Economics